
Conviction Equities
Concentrated and fundamentally driven high-conviction equity portfolios managed by four teams specialized in emerging markets, impact investing, thematic investing, and Switzerland.

Global semiconductor stocks are down 34% from their June peak, with most of the decline since early October, and Emerging Market IT down 31%. The market has effectively priced two amber flags on our AI watch list – financing costs and power and permitting constraints – as red flags. Our analysis suggests both are more likely to delay rather than derail the AI buildout, while EM tech valuations already discount much of the downside. The same conclusion should hold even after Nvidia CEO Jensen Huang stepped down following the affair with an alleged Chinese spy.
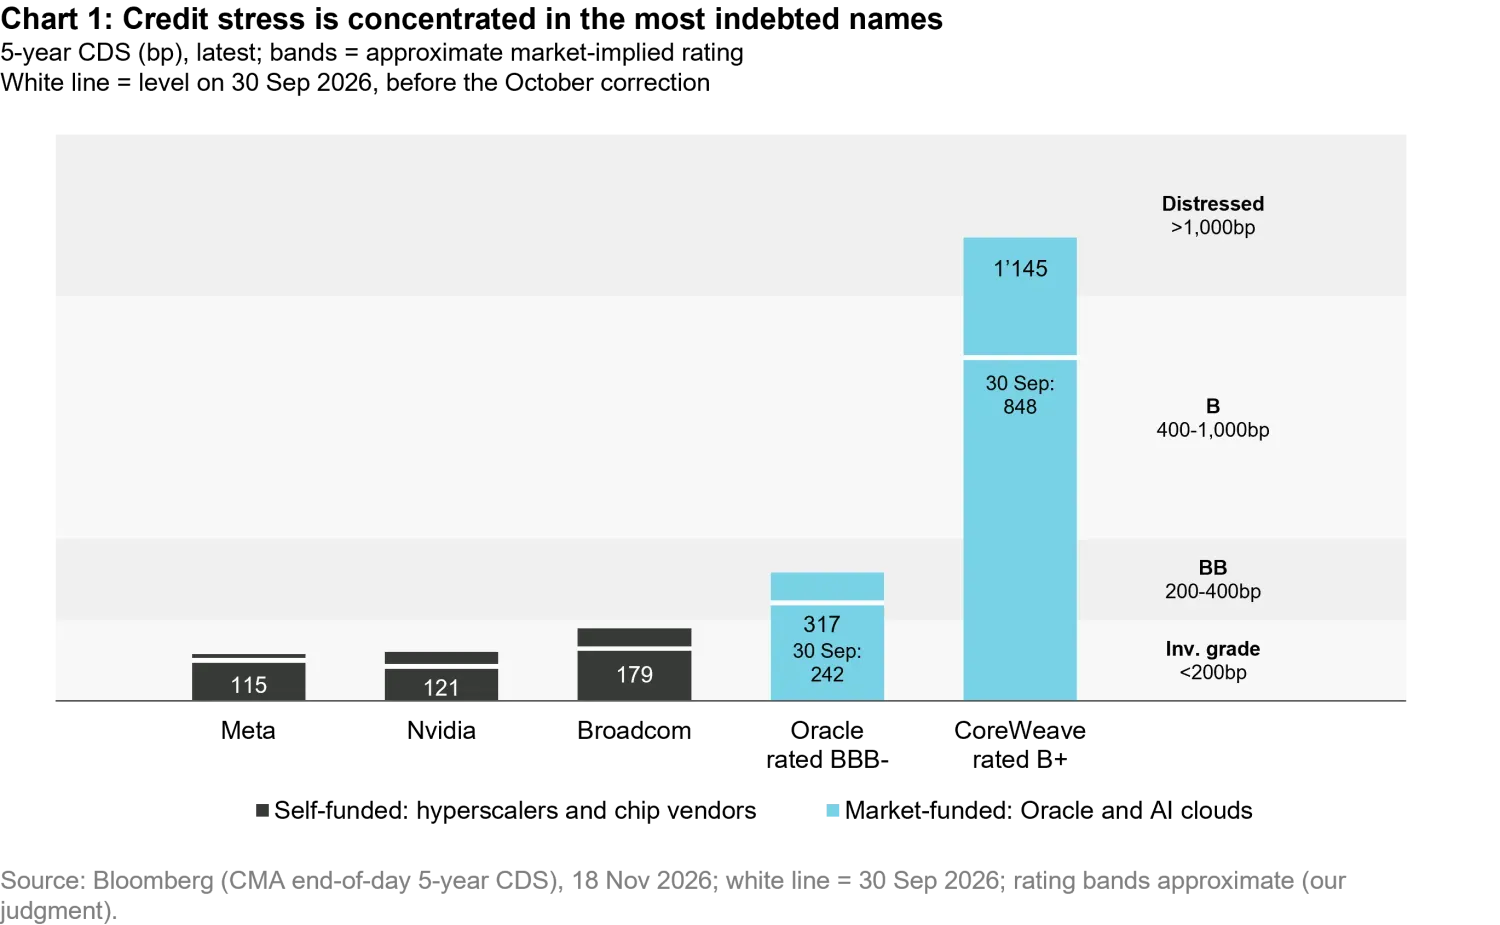
October's selloff started with interest rates, not with demand. Hotter US inflation pushed the 10-year Treasury yield to 5.36% on October 7, its highest since 2002, and credit markets repriced the most indebted part of the AI buildout first. Default protection on CoreWeave, the most leveraged AI cloud provider, rose above 1,000bp — distress territory — and Oracle now trades like a sub-investment-grade borrower despite its BBB- rating. The bigger picture appears reassuring. The largest hyperscalers, which account for most AI capex, fund it primarily from their own cash flow and continue to borrow at investment-grade levels. What tightens is financing at the margin, in particular for independent AI clouds (neoclouds). Yet even there, most debt is secured: around three-quarters of CoreWeave's borrowing is backed by its chips and repaid from signed customer contracts, making material defaults unlikely for now. This suggests that higher credit costs may slow parts of the buildout, but are unlikely to stop it.
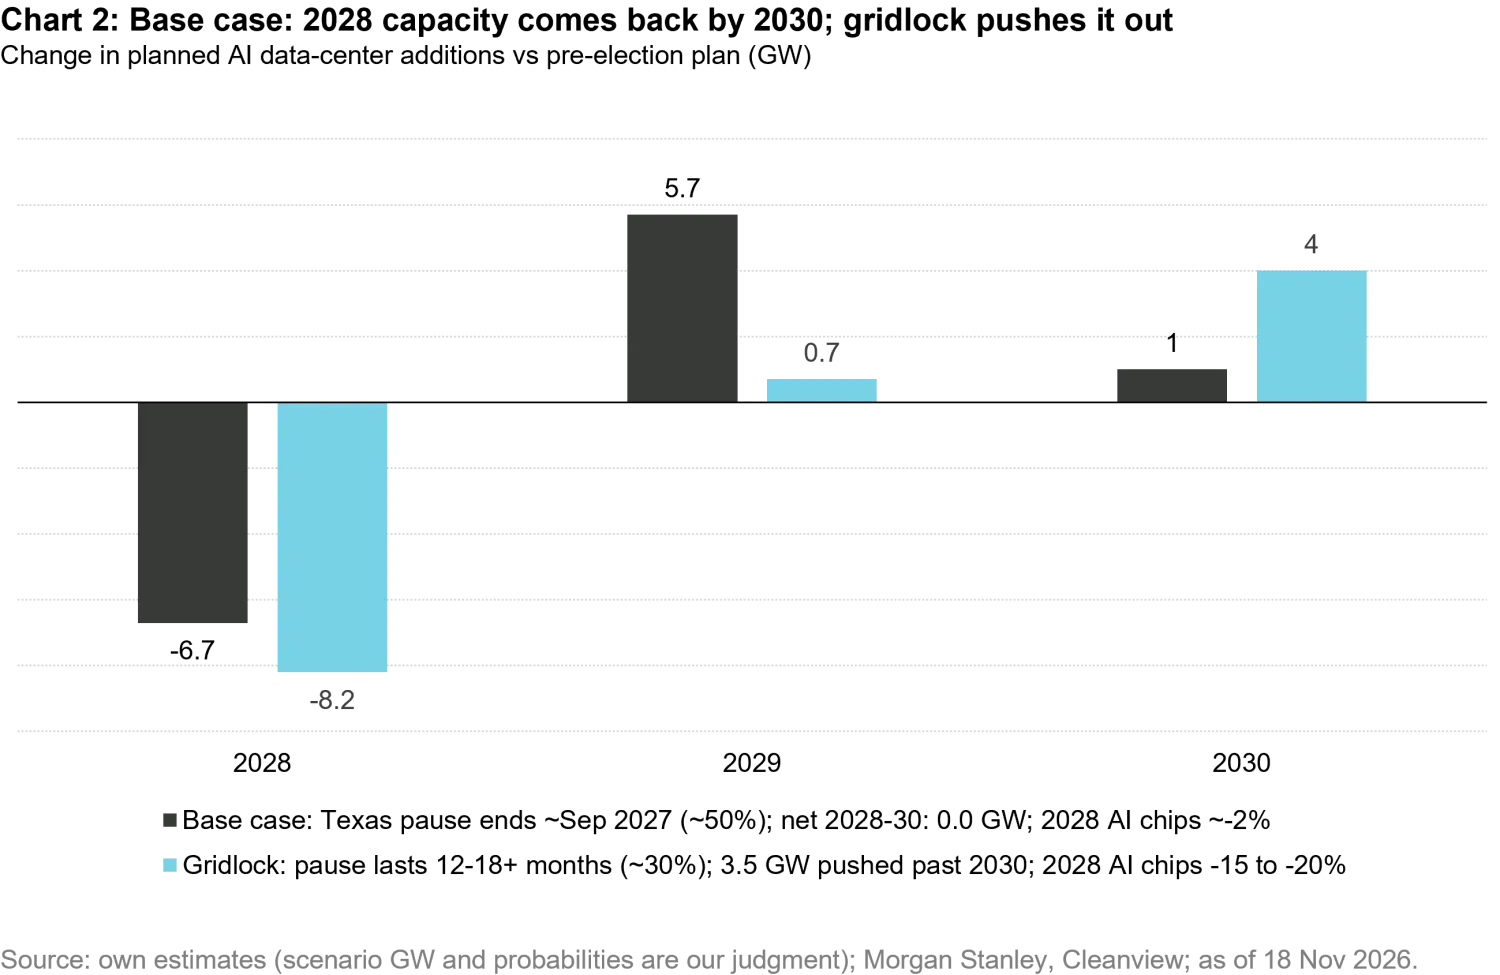
The second, sharper leg of the sell-off came with the midterms. Democrats won key governor races in Texas, Georgia, Ohio, Pennsylvania and Wisconsin, and restrictive proposals gained executive backing: In Texas, the governor-elect has proposed pausing new datacenter permits from 19 January until new rules give communities “a seat at the table”, while Georgia's new utility-commission majority supports a freeze. At first glance, the headline exposure looks alarming: Morgan Stanley counts about 51 GW across 385 projects in the affected states. But this represents the entire multi-year pipeline, not the expected loss. Only part of it is due in any one year, projects already permitted can finish, and the pause mainly hits capacity planned for 2028–29 that still needs permits. In our base case about 6.7 GW of 2028 additions get delayed, nearly all of it into 2029–30, which trims 2028 AI chip demand by about 2%. The key uncertainty is how long the Texas pause lasts. We see three scenarios: with a fast-track resolution ending by spring 2027 (20% likelihood), with a normal solution in the upcoming legislative session ending around September 2027 (50%), or with political gridlock in a divided legislature extending beyond a year (30%). Even in a gridlock scenario we assume capacity to be delayed rather than lost. Since the pause halts new permits until rules are agreed, projects retain their sites and customer contracts. The economic stakes on both sides ultimately favor a deal. And if not reached within the normal legislative period, the governor can call a special session at any time. All that should allow most of the delayed capacity to come online by 2030. Some demand can also move to other states.
Under the gridlock scenario, we estimate 2028 AI chip demand could fall by 15–20%. Probability-weighting the three scenarios implies a 5–7% reduction in 2028 chip demand. This is why we think the market's first reaction overshoots the likely impact.
Then, on November 12, Nvidia CEO Jensen Huang’s resignation following revelations of his affairs, including one involving a suspected Chinese spy, sent renewed shockwaves through markets, given Nvidia’s importance as the leading designer of advanced AI chips and its central role across the AI value chain. With the departure of a charismatic leader that was over thirty years at the helm, some slowdown of decision making and deal activity seems inevitable to us and some market share loss well possible. But the strength of Nvidia’s products and excess demand for AI chips do not disappear with the change in leadership. At the same time, renewed US restrictions on China have added another layer of risk. The US Department of Commerce’s Bureau of Industry and Security issued an interim final rule on 15 November 2026 targeting remote access to advanced AI chips through overseas data centers. Yet independent estimates suggest that Chinese-rented overseas capacity represents only around 4–7% of Nvidia’s annual chip volumes. With AI chips still supply-constrained, much of any affected volume could potentially be redirected to other customers.
For the Asian supply chain, the potential impact of datacenter buildout delays varies by where companies sit along the value chain. Chipmakers such as TSMC remain relatively insulated near term because AI chip supply is still significantly short of demand; only a prolonged delay would eventually feed through into order cuts. More exposed near term are Taiwan's rack-level suppliers, including server, power-supply and cooling companies, where inventories are already elevated and lead times are short. By contrast, grid and facility equipment suppliers are cushioned by multi-year backlogs. Therefore, any loss of Nvidia market share could create opportunities for suppliers tied to hyperscalers’ custom-chip programs such as those developed by Google and Amazon. In any case, valuations have corrected much more sharply than fundamentals would justify, according to our analysis. Global semiconductor stocks trade at 10.9x forward earnings, close to previous cycle troughs, even as earnings are expected to rise through 2028. In our view, valuations therefore already discount much of a gridlock scenario, including a more prolonged buildout delay and a period of inventory digestion. Semis trade at trough multiples, yet earnings should still grow double-digit even in a gridlock.
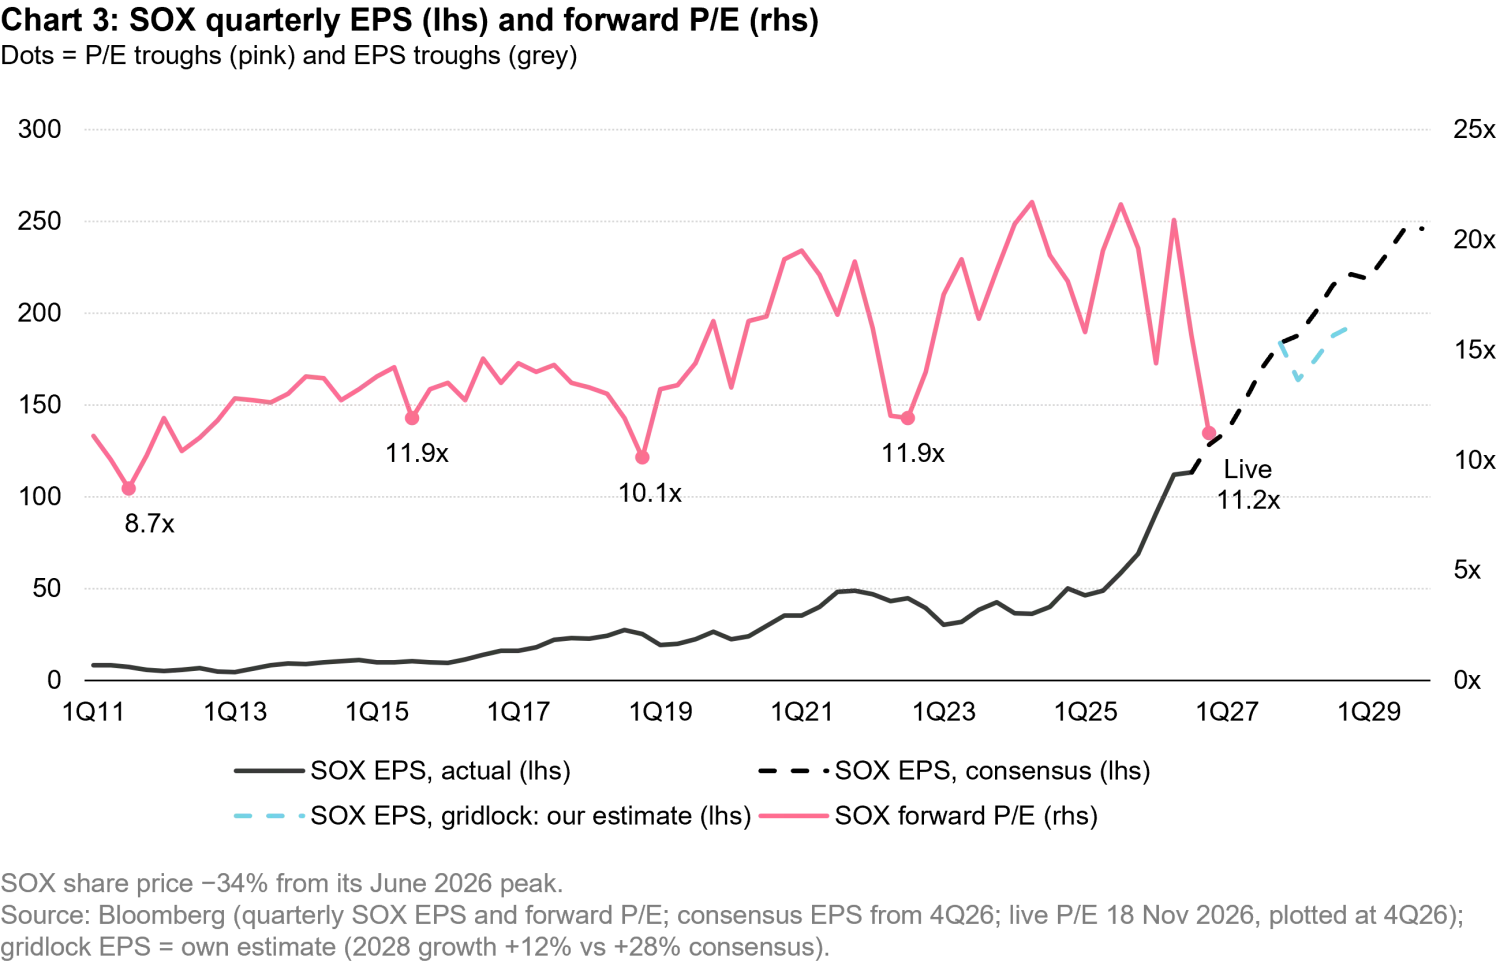
In past cycles, share prices typically bottomed one to three quarters ahead of earnings, but those troughs were followed by falling earnings. This time, even with a Texas pause of more than a year, we would still expect industry earnings to grow at a double-digit rate in 2028 rather than fall.
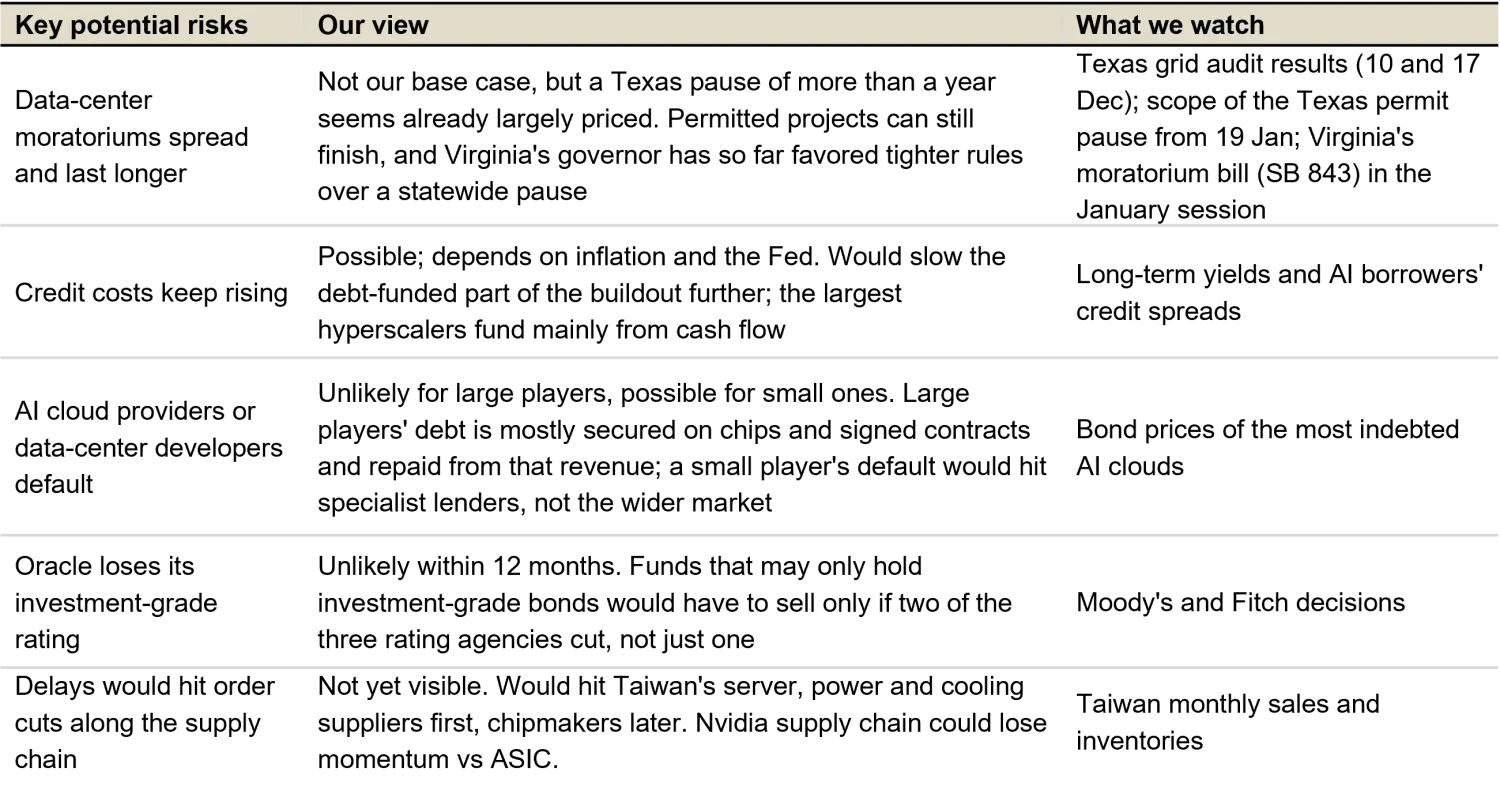
So far, markets have repriced risk, but no AI borrower has defaulted on its debt, and chip orders remain firm. In our view, the key question is whether credit cost headwinds and permitting delays remain manageable and temporary or develop into a broader AI downcycle. Below, we highlight key risks, our current assessment and the signposts we are monitoring.