Key takeaways
- Significant caution is still warranted in positioning as volatility is likely to persist.
- Central bank policies continue to diverge. Political pressure on and influence over the Federal Reserve remain major concerns. The impact of tariffs and the uncertainty around their implementation continue to weigh on markets.
- Geopolitical and global trade risks remain elevated and US isolationism is growing, while China and its allies appear united.
- Credit fundamentals remain strong alongside robust technicals in fixed income markets.
- After a recent pullback, valuations have improved and opportunities persist for active investors focused on alpha.
As volatility continues, opportunities abound for active managers, both in terms of risks to avoid and value to capture. In 2024 and 2025, there were ample opportunities for genuine, high-quality alpha-generative active managers to deliver for their clients. Our team continues to believe that caution is warranted. From this position, by focusing on balance, agility, and liquidity, we see opportunities to generate meaningful alpha to supplement and enhance the returns that fixed income markets can deliver. On a relative value basis, we still favor fixed income broadly over many other asset classes, particularly some of the sub-asset classes that offer high returns relative to risk.
Those of you who know me well will likely be expecting another rant about the markets. My bias undoubtedly leans toward the more bearish side, which makes me well suited for the asymmetric return profile of fixed income. One does not need to look hard to find reasons for concern, some of which have the potential to trigger major sell-offs, the likes of which we saw earlier in the year. The reshaping of global alliances, the impact of tariff policies and US isolationism on global trade, and the significant challenges several central banks are facing are sufficient to warrant extreme caution. Much has been written about these challenges, and each has the ability to stimulate further bouts of volatility.
And yet our risk appetite view remains mildly positive. In short, we are enjoying these markets and wish to continue participating in them. Technicals within fixed income markets are robust, as evidenced by the asset class’s relative outperformance post “Liberation Day.” Cash balances among managers remain high, and the wall of money sitting in money-market funds waiting to be returned to more traditional fixed income markets should sound a note of caution for anyone wishing to hold a bearish position for the medium or long term.
And so, the balance between fear and greed sits finely poised – except for one factor that underscores our confidence in fixed income: credit fundamentals.
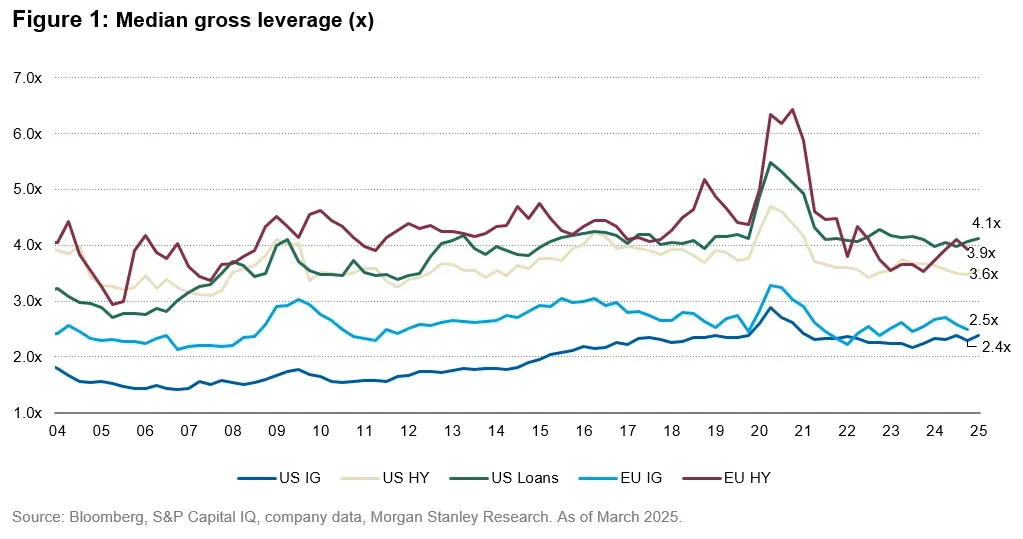
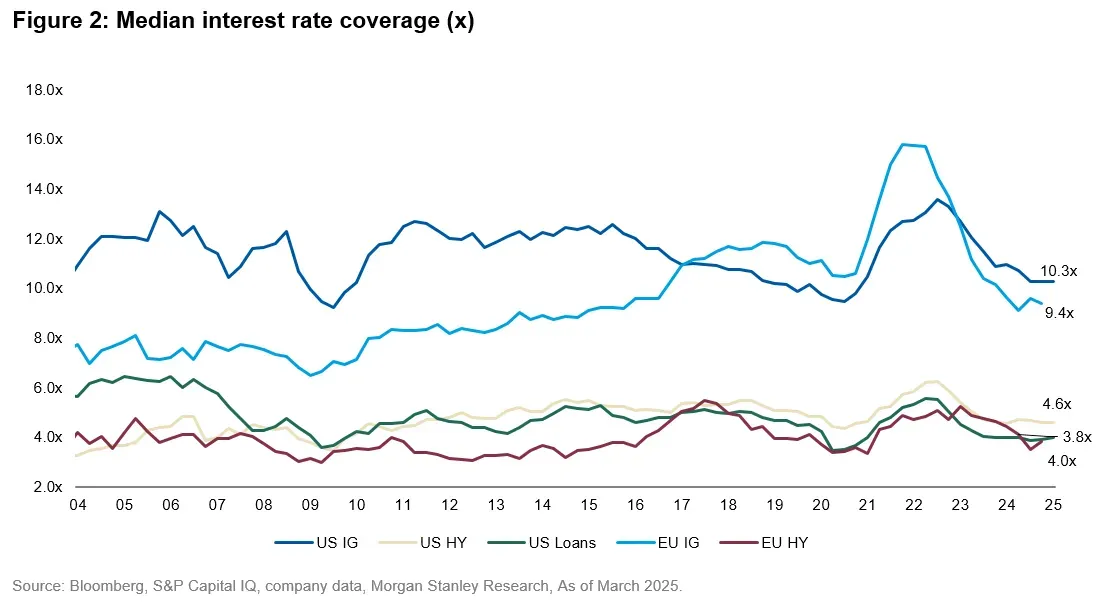
Wherever one looks, credit fundamentals are surprisingly robust, given where we are in the credit cycle. European banks look solid, emerging market sovereigns and corporates maintain strong debt sustainability, and investment grade corporates continue to avoid equity-friendly profligacy. Consumers are displaying surprisingly strong performance, with manageable debt levels, and even the high yield segments in the US and Europe exhibit strong credit fundamentals.
That said, these observations are all based on averages, and there are undoubtedly caveats that lead to our caution. Most notably, we see high yield borrowers being the most exposed to deteriorations in economic conditions and most susceptible to periods of market volatility that could affect their ability to refinance debt.
Stay cautious, stay nimble, and enjoy these markets.